

Loan Calc Hub analysis by Appwee
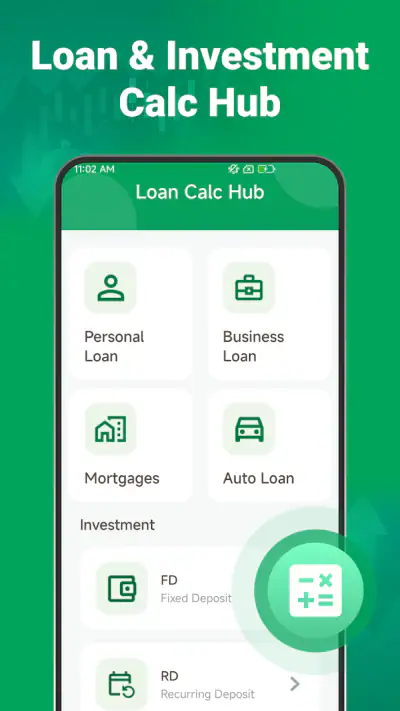
Loan Calc Hub is the kind of finance app I reach for when I need a quick answer before making a bigger decision. It is built around three practical jobs: checking loan repayments, estimating fixed-deposit returns, and exploring recurring investments. That sounds straightforward, and the app’s appeal is exactly that it keeps these calculations together instead of making me search for separate tools.
My first impression is that it is best treated as a planning calculator, not as a banking service or financial adviser. I can use it to compare possibilities, test a few amounts, and spot whether a proposed payment fits comfortably into my budget. I would not use a result as the only reason to sign a contract, because real lenders and investment providers may apply charges, taxes, changing rates, or rules that a simple estimate cannot fully represent.
Developed by AppDsgnur, the free app sits in the finance category and is suitable for Everyone. It has passed the one-million-install mark and holds an average rating of 3.5 from around one thousand ratings, which suggests a useful but not universally smooth experience. The current release is version 1.1.0.0, and it requires Android 9 or newer. Those details matter if an older phone is involved or if someone expects the calculator to behave like a full account-management app.
Where the calculation experience can become confusing
Choosing the right calculation before entering numbers
The first place I would expect a new user to hesitate is not the arithmetic; it is deciding which type of estimate matches the question in front of them. A loan repayment calculation answers a borrowing question. A fixed-deposit estimate looks at money placed for a set term. A recurring-investment calculation deals with repeated contributions. Mixing these categories can produce a neat-looking result that answers the wrong question.
I find it helpful to write down the decision in plain language first. If I am asking, “What might I pay each month after borrowing?” I use the loan side. If I am asking, “What could a one-time deposit become by the end of its term?” I use the fixed-deposit side. If I am setting aside money regularly, I use the recurring-investment side. This small pause prevents the common mistake of treating every result as an interchangeable return or payment figure.
Why a result can look more certain than it really is
A calculator naturally presents a clean number, while financial products are often messy. A loan offer may include processing costs, insurance, penalties, a changing interest rate, or a different repayment schedule. A deposit may have conditions around early withdrawal. A recurring investment may not grow at a fixed rate at all. Loan Calc Hub is useful for isolating the basic calculation, but I would keep those real-world details beside the result rather than mentally folding them into it without checking.
One of my preferred habits is to run a small range instead of a single optimistic scenario. I might test a lower and higher rate, a shorter and longer term, or a smaller and larger recurring contribution. The point is not to predict the future perfectly. It is to see how sensitive the decision is. If a small change makes the payment uncomfortable, that is more important than the prettiest estimate on the screen.
The everyday situation where it earns its place
Imagine I am considering a used car and have already decided how much I can put down. Before contacting a lender, I can use the loan calculator to explore whether the remaining amount feels manageable over different terms. I can then compare that monthly figure with fuel, insurance, maintenance, and existing bills. The app does not replace a lender’s formal quote, but it helps me avoid starting a conversation with an unrealistic budget.
The same approach works for saving. If I want to build a future fund through regular contributions, I can test what happens when I change the contribution amount or the expected return. That makes the decision more concrete than simply saying I should save more. The useful insight is often not the final total but the trade-off between contributing comfortably and chasing a larger projected balance.
Who benefits most from the simple layout
I think the strongest audience is someone who wants quick comparisons without opening a spreadsheet. A first-time borrower, a household planning a purchase, or a saver comparing a lump sum with regular contributions can all get value from the focused design. It is also handy for a conversation: I can adjust one assumption while discussing a budget instead of rebuilding a formula from scratch.
On the other hand, people who need detailed amortization schedules, tax treatment, portfolio tracking, lender-specific rules, or account connectivity should look elsewhere. A specialist financial calculator or spreadsheet will usually offer deeper control. Someone managing an active loan or investment account also needs the provider’s own figures, because an estimate is not a transaction record.
Setup checks that prevent avoidable problems
Start with the phone and installation basics
Because the app requires Android 9 or newer, I would check the phone’s Android version before spending time troubleshooting an installation problem. If the device is older, an inability to install or update is likely a compatibility issue rather than a calculation fault. On a supported phone, I would make sure the installation has finished properly and then reopen the app before entering important figures.
Loan Calc Hub is free, which removes a purchase decision from the setup process, but “free” does not mean that every financial question is covered automatically. The useful preparation is having the figures ready: principal or deposit amount, rate, term, and contribution frequency where relevant. If I do not know what a rate represents, I would pause and check the provider’s wording instead of guessing.
Prepare inputs in the same units as the real offer
Many disappointing results come from inconsistent units. A monthly repayment estimate should be compared with a monthly household budget. A yearly rate should not be casually entered as though it were a monthly rate. A term expressed in years needs to be understood in relation to the payment schedule. Before tapping calculate, I would read each field label carefully and convert my notes into the format the screen requests.
This is especially important when comparing a bank’s quote with a personal estimate. Banks may describe a rate as annual, effective, nominal, fixed, or variable. Those labels are not decorative. If the app asks for a basic rate but the quote includes a different compounding method, the result may only be a rough comparison. I would record the assumptions next to the result so I remember what the number actually means later.
Use clean test values before relying on a result
My setup routine would begin with an easy example: a round amount, a simple term, and a rate I can reason about. This is not about proving the app mathematically; it is a way to notice whether I have selected the wrong calculator or entered a decimal incorrectly. Once the workflow makes sense, I would replace the test values with the real scenario.
I also avoid changing several fields at once. If I alter the amount, rate, and term together, I cannot tell which change caused the result to move. Changing one assumption at a time makes the app more useful as a comparison tool. It also reveals an important trade-off: a longer loan term may reduce the regular payment while increasing the total cost, whereas a higher recurring contribution may require more discipline today for a larger projected balance later.
Keep the app’s role clear during setup
The age rating of Everyone makes it approachable for general use, but financial decisions still require adult judgment and careful checking. I would not enter sensitive account credentials or treat the calculator as a secure place to manage money. Its value is in working with figures, not in replacing a bank, broker, or deposit provider.
That distinction answers a question many people have before installing: can this app complete a loan application or open an investment? I would use it for estimates only. Any application, transfer, confirmation, or legally binding rate must come from the relevant financial institution. Keeping that boundary clear makes the tool safer and prevents a planning number from being mistaken for an approved offer.
Recovering when a workflow does not go as expected
Reset the thought process before blaming the calculation
If a result looks strange, my first recovery step is to return to the question rather than immediately repeat the calculation. Am I estimating a payment, a deposit maturity value, or recurring growth? Did I enter the amount I will borrow, or the purchase price before my down payment? Did I use the provider’s rate in the same form the calculator expects? These checks solve more problems than repeatedly tapping the calculate control.
I would then clear the scenario mentally by entering a simple set of values again. If the simple case behaves sensibly, the issue was probably an input or interpretation problem. If the app stops responding or refuses to proceed, I would close and reopen it, confirm that the phone is on a supported Android version, and try a fresh calculation. Those are sensible general recovery steps without assuming a specific technical cause.
Compare the result with an independent rough check
A second calculator, a spreadsheet, or the lender’s own illustration can be useful as a comparison. I do not expect every tool to display identical results when compounding, rounding, fees, or timing differ, but a major gap deserves investigation. The goal is not to find the number I like best. It is to understand which assumptions each tool is using.
For a loan, I would compare the estimated regular payment with the provider’s formal illustration and ask whether the illustration includes fees or optional products. For a fixed deposit, I would check whether the quoted return is before or after any applicable deductions. For recurring investments, I would treat the output as a projection rather than a promise and test what happens if the expected return is lower.
Recover from a misleadingly attractive scenario
The most dangerous workflow is one that works perfectly but encourages overconfidence. A low payment can make a long loan look comfortable, even though the total repayment may be much higher. A large projected investment balance can hide the fact that the assumed return is uncertain. A fixed-deposit estimate can appear reassuring until I consider whether I may need the money early.
My practical fix is to create a “stress” version of every important scenario. I increase the borrowing cost, reduce the expected return, or lower the amount I can contribute. Then I ask whether the plan still works. This is one of the app’s best uses beyond its store summary: it turns a single estimate into a small decision exercise, provided I remember that the quality of the answer depends on the assumptions I enter.
When an update or device change enters the picture
The current version is 1.1.0.0, so I would note the version when comparing a result with something seen on another device or at another time. If the interface changes after an update, I would reread the field labels instead of assuming that every control behaves exactly as before. I would also avoid copying an old result without its assumptions, because the number is only meaningful alongside the amount, rate, term, and contribution pattern that produced it.
If the app becomes unavailable after a phone change, I would first confirm that the new device meets the Android requirement and that the installation completed normally. I would keep important calculations in my own notes, including the inputs and the date I ran them, rather than relying on memory. That habit is useful with any calculator because it makes later comparisons possible and exposes when a provider has changed its actual offer.
When the app is not the cause of the problem
Provider terminology can be the real source of confusion
A calculator cannot correct an unclear quote. If a lender uses one rate for advertising and another for the final offer, the difference may come from eligibility, fees, or the way interest is calculated. If a deposit provider quotes a return for a particular term, withdrawing early may change the outcome. If an investment illustration assumes regular contributions at a precise interval, missed payments can alter the projection.
In each case, I would treat Loan Calc Hub as the neutral comparison layer and the provider’s terms as the authority for the actual product. The app can show what happens under an assumption; it cannot decide whether that assumption applies to me. This is why I would never judge the app solely because its estimate differs from a marketing example without first checking the definitions behind both figures.
Rounding and timing can create small differences
Even when two calculations use the same broad inputs, rounding may happen at different stages. One tool may round each payment, while another keeps more decimal places until the end. Payment timing can matter too: contributions at the beginning of a period do not grow in exactly the same way as contributions at the end. A small difference is not automatically a defect.
What matters is whether I can explain the difference. If I cannot, I would avoid making a major decision from either result until I understand the assumptions. For everyday planning, a close estimate may be enough to decide whether a budget is broadly realistic. For signing a contract, I would use the official schedule and ask the provider to explain any unclear charges.
Personal affordability is broader than the displayed payment
Loan Calc Hub can help me focus on a repayment figure, but affordability includes irregular costs and financial resilience. A payment that fits on paper may become difficult after rent changes, repairs, medical expenses, or an income interruption. I would leave room in the household budget instead of treating the maximum comfortable payment as the target.
The same caution applies to recurring investments. A contribution plan is only useful if I can maintain it without repeatedly sacrificing essential spending. I would rather test a modest amount that remains realistic than choose an impressive projection that depends on perfect discipline. The app is strongest when it supports that honest conversation with myself.
When another tool is the better choice
I would choose a bank’s calculator when I need the bank’s exact product rules, a spreadsheet when I want a detailed schedule or custom formulas, and a portfolio platform when I need actual investment tracking. A financial adviser may be more appropriate when taxes, complex assets, business borrowing, or significant risk are involved.
That does not make Loan Calc Hub unnecessary. Its advantage is speed and focus. It gives me a convenient starting point for three common planning tasks without forcing me into a full financial system. The trade-off is limited depth: I gain a quicker first estimate, but I must do more of the interpretation and verification myself.
My practical verdict after using it as a planning companion
Loan Calc Hub is most valuable as a first-pass decision tool. I can use it to turn vague questions into comparable scenarios, especially before speaking with a lender or deciding how much to save regularly. The free price and broad Everyone rating make it easy to approach, while the one-million-plus install base indicates that it has reached a substantial audience. Its 3.5 average also sets a sensible expectation: useful for many people, but not something I would assume is flawless in every situation.
I would recommend it to someone who wants a compact way to explore loan payments, fixed deposits, and recurring investments on an Android phone. I would tell that person to prepare the inputs, check the units, save the assumptions, and run a stress scenario before trusting the conclusion. Those habits matter more than simply pressing calculate.
I would skip it if I needed a full financial dashboard, live account information, detailed amortization, or product-specific legal and tax treatment. In those cases, a provider’s official tools or a more advanced calculator will be a better fit. I would also avoid using it as a substitute for professional advice when the decision is unusually large or complicated.
For ordinary planning, though, I like the role it plays. It does not need to pretend to be a bank or an investment platform to be useful. When I keep its estimates in context, the app helps me ask better financial questions before committing real money. That is a modest purpose, but it is a practical one, and it is where Loan Calc Hub makes the most sense.
Gallery
Loan Calc Hub Pros and Cons
- Quickly estimates loan payments
- interest
- and total repayment costs.
- Supports comparisons between different loan amounts
- rates
- and terms.
- Simple interface makes calculations accessible for first-time borrowers.
- Useful for budgeting before applying for a personal or auto loan.
- Works as a convenient reference tool without contacting a lender.
- Results are estimates and may exclude lender fees
- taxes
- or insurance.
- Does not guarantee approval or reflect personalized lender offers.
- Variable-rate loans may produce different payments over time.
- Users must enter accurate figures to avoid misleading calculations.
- Financial guidance and lender-specific features may be limited.
Loan Calc Hub Frequently Asked Questions
What is Loan Calc Hub used for?
Loan Calc Hub is designed to help users estimate the cost of borrowing before applying for a loan. After entering details such as the principal amount, interest rate, loan term, and payment frequency, the app can provide an estimated repayment schedule, periodic payment, total interest, and overall repayment amount. It is mainly a planning and comparison tool, not a lender or loan approval service.
Can Loan Calc Hub calculate different types of loans?
The app is most useful for common installment-loan calculations, including personal loans, auto financing, mortgages, and other borrowing arrangements with regular payments. Depending on the available calculator options, you may be able to compare fixed interest rates, loan durations, payment intervals, or extra repayments. Results can vary when a real loan includes fees, variable rates, insurance, taxes, or unusual repayment conditions.
Are the calculations from Loan Calc Hub accurate?
Loan Calc Hub can provide helpful estimates when the information entered is correct and the selected calculation method matches the lender’s terms. However, the displayed figures should not be treated as an official quote. Lenders may use different compounding methods, rounding rules, fees, promotional rates, or payment dates. Always compare the app’s estimate with the final agreement and confirm the details directly with the financial provider.
Does Loan Calc Hub apply for loans or connect users with lenders?
Loan Calc Hub is intended for calculating and reviewing loan scenarios rather than approving or issuing credit. Using the calculator does not guarantee acceptance, a specific interest rate, or a particular repayment amount. Users should be cautious of any service requesting sensitive information or upfront payment in exchange for approval. Before sharing personal or financial data, verify whether the app includes any external referral features and review its privacy terms.
What information should I prepare before using Loan Calc Hub?
To get a useful estimate, prepare the amount you plan to borrow, the annual interest rate, the expected loan term, and the preferred payment frequency. If available, also include origination fees, early-repayment charges, taxes, insurance, or an existing balance. Testing several terms and rates can help you understand affordability, but remember that the result is only an estimate and should not replace professional financial advice.














